Executive Summary
Disruptor Profiles are competitive briefs on the non-traditional players competing with health systems: what they have bought, where they operate, and how they change the competitive math. This set covers the three major national pharmaceutical distributors that have spent the past few years buying the physician platforms that serve independent physicians.
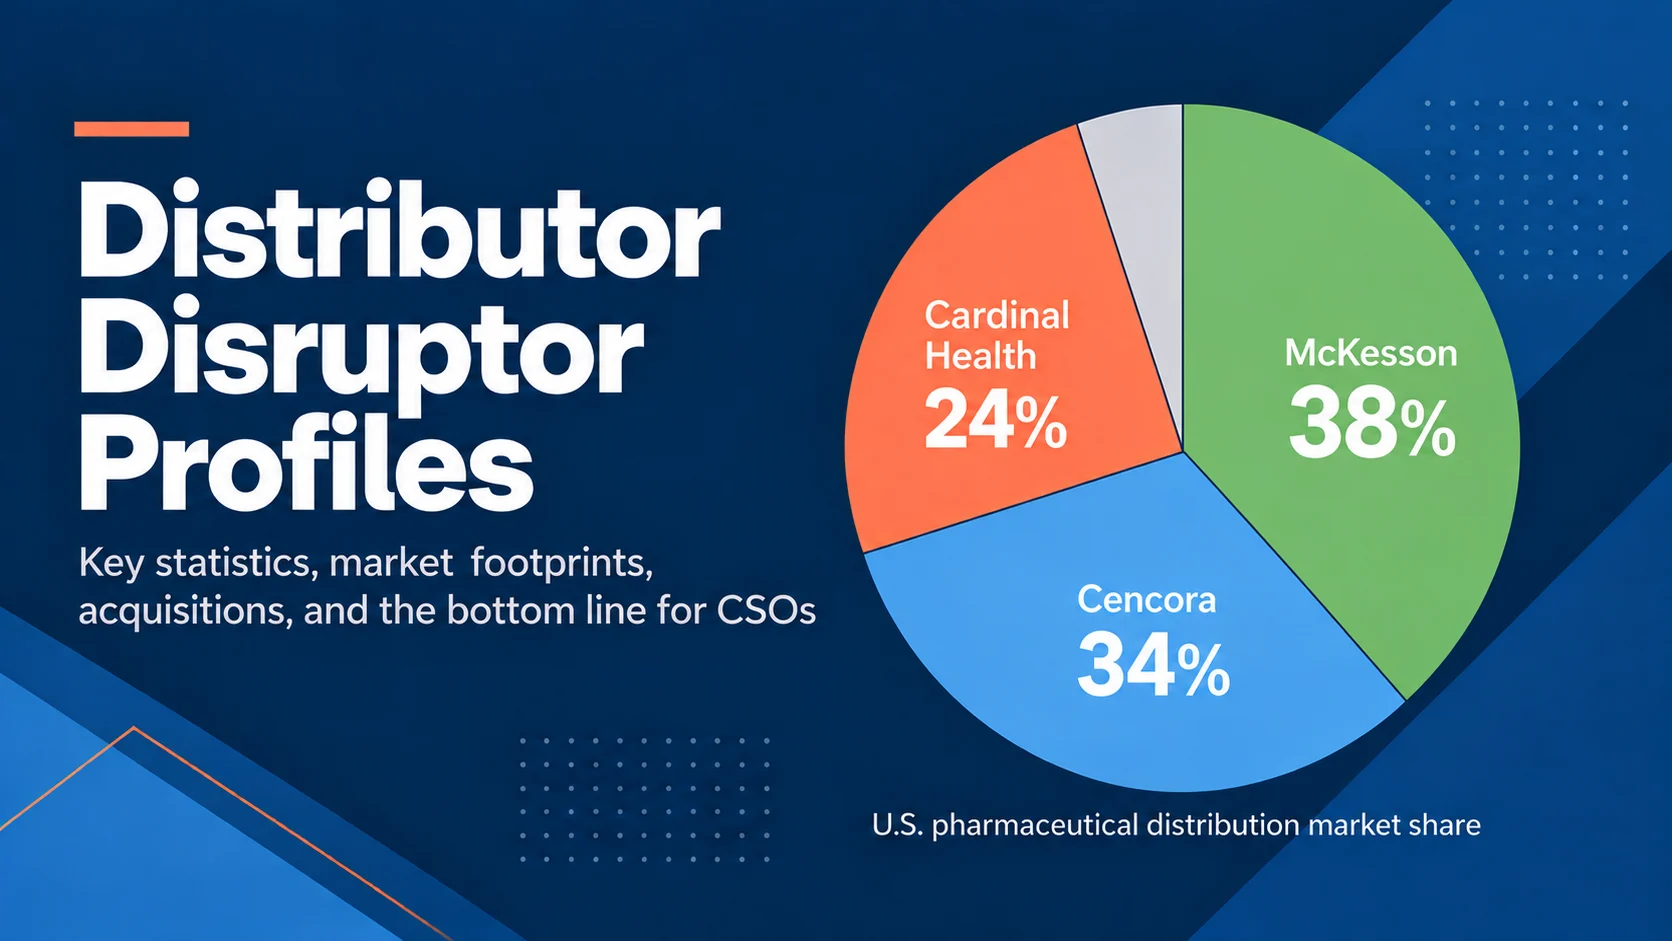
The distributor threat is substantial and growing. McKesson, Cencora, and Cardinal Health control ~96% of U.S. pharmaceutical distribution and have spent over $19B acquiring physician MSOs since 2024.
Distributors with management services organization (MSO) platforms profit from the same drug twice, first from the wholesale margin and then the share of the buy-and-bill revenue from the independent practices they support. For the health system, the drugs, procedures and ancillaries that follow the physician are the exposure.
Oncology is the beachhead, but distributors are rapidly diversifying into other specialties. Cencora and McKesson have concentrated on retina/ophthalmology while Cardinal has expanded into GI and urology. They have acquired the majority in physician MSOs and have added practices through tuck-in acquisitions and affiliations.
Four developments will signal how the distributors’ specialty platforms evolve: Cencora’s EyeSouth closing; McKesson’s Option Care Health closing; Cardinal’s ability to acquire the remaining GI Alliance equity beginning around January 2028; and any distributor moving into a new specialty vertical.
Bottom line for health systems: Compete for the physicians with a better employment or alignment offer. Partner with the distributor platform where it makes sense. Manage supplier dependency since the company supplying the system's drugs may back practices competing with its service lines.